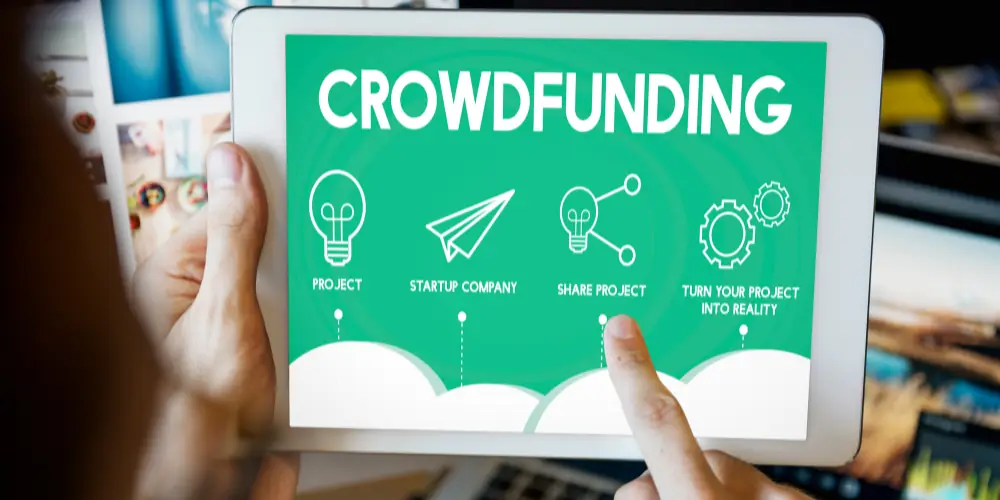
For countless families, crowdfunding has turned into a lifeline during sudden financial crises. GoFundMe and similar platforms allow loved ones—and even strangers—to chip in for overwhelming expenses like hospital bills, memorials, or other urgent costs. Still, the help it provides is usually short-term and rarely addresses long-term stability.
The concern is clear: goodwill has limits. Without reliable financial strategies, people risk depending on uncertain donations when steadier protections—like insurance or savings—might be available.
Crowdfunding’s Role in Emergencies
That said, these platforms have undeniably changed how families cope with tragedy. In the wake of sudden loss or illness, online fundraising often brings fast relief, making a difficult situation a little more bearable.
Yet, while crowdfunding works well in emergencies, it is not designed to cover predictable expenses. Campaigns often appear for situations like car repairs, home maintenance, or retirement planning—needs that can be anticipated and budgeted for. Depending solely on public generosity for these expenses can leave households financially vulnerable.
Risk of Relying Too Heavily on Crowdfunding
One challenge with crowdfunding is its unpredictability. Success depends on visibility, timing, and donors’ willingness to give. A campaign may raise thousands—or nothing at all. Building personal financial security on such uncertainty leaves little stability for the future.
Financial experts emphasize the need to be clear-eyed about crowdfunding’s limits. It can ease sudden crises, but it’s not a plan for predictable life events like buying a car, maintaining a home, or preparing for end-of-life costs. Those responsibilities are better met through savings and insurance.
Steps Toward Stronger Financial Preparedness
Building your own safety net offers stability that crowdfunding can’t. A few practical steps include:
Start an emergency fund – Small, steady contributions add up to a cushion for unplanned expenses.
Keep saving after big goals – Once you’ve reached a milestone, like buying a car, continue setting money aside to cover upkeep or future needs.
Take out life insurance – Even modest coverage can shield loved ones from financial hardship.
Budget for the long term – Set aside funds for healthcare, retirement, and ongoing home maintenance.
These habits create a foundation of security, reducing the need to rely on unpredictable community support.
Building Habits That Last
The key is consistency. Savings and insurance only work when maintained over time. Too often, people stop saving after meeting a specific goal, which leaves them unprepared for the next expense. Continuing the practice—even in small amounts—establishes long-term stability.
By treating savings as a non-negotiable habit, much like paying bills, individuals can gradually strengthen their financial security. Over time, this reduces the need for emergency crowdfunding campaigns, allowing community fundraising to remain what it was originally intended for—extra help during true crises.
Planning First, Crowdfunding Second
Crowdfunding offers comfort in the moment, yet it falls short as a reliable safety net. Depending on uncertain donations for costs that can be planned for leads to greater fragility. The smarter approach is to focus on savings, maintain affordable insurance, and adopt consistent habits that protect financial well-being.
By doing so, crowdfunding can return to its rightful place—as a supportive resource in extraordinary times—while financial stability is built through deliberate, ongoing preparation.