A 401(k) rollover can look like a simple retirement move after leaving a job. Moving the money into an IRA may offer more investment choices, but the decision can also mean giving up protections and benefits that came with the employer plan.
A recent CFP Board guide on fiduciary duty in rollovers warns that retirees do not have to roll over their savings and, in most cases, cannot reverse the decision once the money moves.
The amount of money involved is significant. Cerulli Associates estimates that about $941 billion will move from 401(k) plans into IRAs in 2026. Annual rollover flows could reach $1.3 trillion by 2031.
At the same time, more than 11,000 Americans are turning 65 each day in 2026, according to the Alliance for Lifetime Income. The Investment Company Institute reports that IRAs held about $18.2 trillion in the first quarter of 2026.
With so much retirement money changing accounts, understanding the trade-offs matters.
Most Rollovers Cannot Be Reversed
Once 401(k) funds enter an IRA, returning the money to the former employer’s plan usually is not an option.
“Once the money is in an IRA, you can’t go back to whence you came,” Brenton Harrison, a certified financial planner in Nashville, told CNBC.
Former employees generally can leave their savings in an old 401(k), although relatively few retirees choose that route. According to the Plan Sponsor Council of America, cited in the CFP Board guide, fewer than half of retirees keep their assets in the employer plan in roughly 77% of 401(k) plans.
There are exceptions. The federal Thrift Savings Plan, for example, accepts rollovers from former federal employees under certain conditions, according to the CFP Board guide.
What Could Be Lost
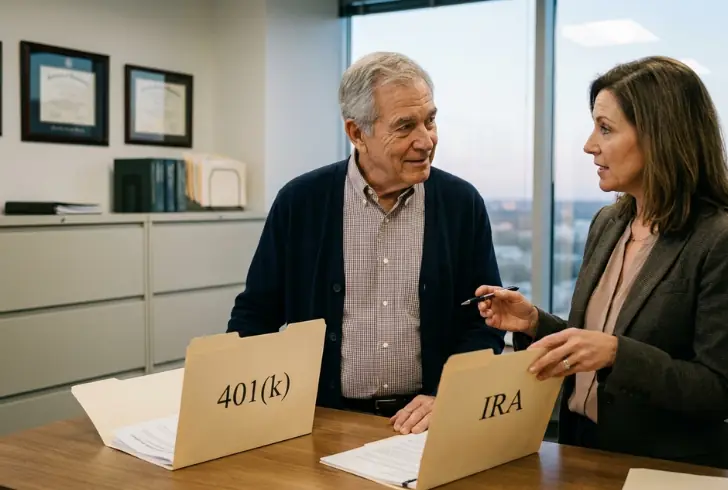
A rollover can change more than the account statement. It can also affect investment costs, creditor protection and the level of oversight surrounding financial advice.
1. Institutional Pricing
Large employer plans often negotiate lower investment costs because thousands of employees invest through the same plan. An IRA generally uses retail investment pricing, which can be higher for comparable funds.
The difference may look small at first. The SEC has shown that a 0.75-percentage-point difference in annual costs on a $100,000 portfolio could reduce the account’s value by about $29,000 over 20 years.
That makes a direct fee comparison worth doing before transferring the money.
2. Creditor Protection
ERISA-covered employer retirement plans receive broad federal creditor protection, including protection inside and outside bankruptcy.
IRA protection works differently. Rollover assets generally receive federal bankruptcy protection under a tracing rule. Outside bankruptcy, however, protection depends on state law. Those rules vary considerably. Some states provide broad protection, while others use standards based on financial need or a court’s decision.
The change may be easy to miss during a rollover, but it can matter depending on a retiree’s circumstances and state of residence.
3. Rollover Advice
The regulatory framework around rollover recommendations also changed in 2026. Janus Henderson reported that the rule governing conflicted rollover recommendations was vacated in March 2026.
The Department of Labor restored the 1975 five-part fiduciary test in place of the vacated 2024 rule. According to Janus Henderson and the March 20, 2026, Federal Register notice, that older test is narrower and generally does not treat a one-time rollover recommendation as fiduciary advice.
Five Questions to Ask
A rollover decision deserves more than a quick comparison of investment menus. Brian Wong, assistant general counsel for standards at the CFP Board, told Financial Planning that poor or conflicted rollover advice can expose clients to “unnecessary costs or significant tax penalties.”
Ellen Lander, founder of Renaissance Benefit Advisors Group, has also argued that the advantages and disadvantages of keeping money in a 401(k) versus moving it to an IRA are not discussed often enough.
Before signing rollover paperwork, retirees should examine five areas.
Are IRA fees really lower?
Request the 401(k)’s fee schedule and compare it with the IRA provider’s expenses and available funds. CNBC cited financial advisors who recommend making this comparison before moving money. David Blanchett, a certified financial planner and head of retirement research at Prudential Financial, told CNBC that “all the money in IRAs is coming from rollovers,” which makes the cost difference especially relevant.
Will creditor protection change?
Check the IRA protection rules in the state where the account holder lives. IRA Financial notes that protection outside bankruptcy depends on state law.
Is the advisor acting as a fiduciary?
Brian Wong recommends asking whether the person giving advice operates as a fiduciary or under the SEC’s Regulation Best Interest standard. Financial Planning reported that even when a client directs a rollover, advisors must disclose information that could lead a prudent professional to conclude that the transaction is not in the client’s best interests.
Could penalty-free access before age 59½ matter?
Moving funds can eliminate access to the Rule of 55. That provision can allow penalty-free withdrawals from a 401(k) after leaving an employer at age 55 or older, subject to its requirements.
Will the money actually be invested?
The destination account matters only if the retirement savings are put to work appropriately. Vanguard found that 28% of investors who moved money into a Vanguard IRA in 2022 still held the assets in cash 12 months later. Vanguard also found that rollover cash left uninvested often stays that way for at least seven years.
Andy Reed, head of investor behavior research at Vanguard, described the issue as “a widespread, enduring, and costly problem.”
Impact on Your Retirement Income
A 401(k) rollover may make sense in some situations, but convenience alone does not settle the question. Once the money leaves an employer plan, certain protections and withdrawal options may become unavailable.
The right comparison should include fees, investment choices, creditor protection, withdrawal rules, tax considerations and the quality of the advice behind the recommendation. Keeping the money in the former employer’s plan can also remain a valid option.
Retirement savings are difficult to replace once fees, taxes or investment decisions reduce the balance. With rollover activity expected to reach hundreds of billions of dollars in 2026, retirees have good reason to examine the details before signing transfer documents.
A careful comparison can show whether an IRA genuinely improves the retirement strategy or simply moves the money into an account with fewer protections and different costs.