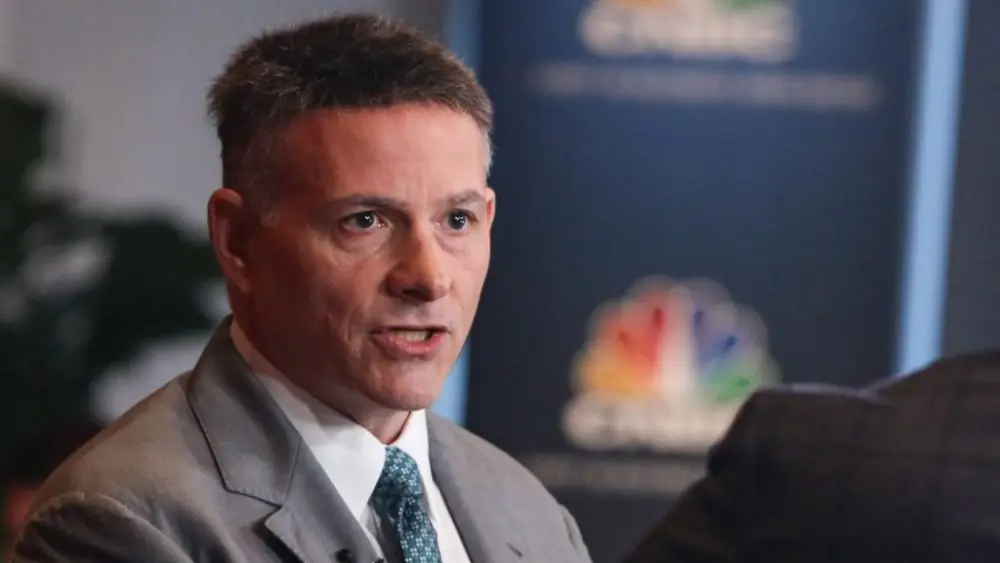
David Einhorn, founder and president of Greenlight Capital, has a bold vision for Peloton. He believes the struggling fitness company could see a five-fold increase in value. The catch? Only if it makes some big cost cuts. In a recent pitch at the Robin Hood Investors Conference, he laid out a persuasive case, showing how Peloton could transform its business and reach a share price far beyond current levels.
Einhorn’s perspective on Peloton’s future offers an intriguing look at how a smart financial strategy and disciplined cost structure could revive the brand.
Peloton has been on a financial rollercoaster since its rapid rise during the pandemic. With a series of missteps and shifting consumer demand, the brand has seen its value plummet, but Einhorn thinks there is still hope. He argues that, with the right cost-saving measures, Peloton could bring in about $450 million in EBITDA, effectively doubling its current projection.
According to Einhorn, this increased profitability could send Peloton shares soaring to between $7.50 and $31.50. Greenlight Capital’s own investment in Peloton shows that his confidence is not mere talk. It is backed by a $6.8 million stake.
What Cutting Costs Could Mean for Peloton’s Future?
For Einhorn, cutting costs isn’t about shrinking Peloton’s vision. Instead, it is about realigning the business to survive and thrive in a competitive landscape. If Peloton manages to trim down its expenses, it could increase profitability and give shareholders a reason to get excited again. Einhorn’s analysis suggests that Peloton’s high operating costs are holding the company back, making it harder to achieve sustainable profits.
To put things in perspective, Einhorn compared Peloton with companies like Planet Fitness, Chewy, Spotify, and Netflix, focusing on how these brands manage their expenses relative to their revenue.
In Einhorn’s view, Peloton should prioritize a leaner approach that allows the company to maintain core product quality without unnecessary expenses. This could mean rethinking marketing budgets, consolidating supply chains, or reducing overhead in ways that wouldn’t impact customer experience. According to Einhorn, this efficiency would boost Peloton’s share price to between $7.50 and $31.50.
Can Peloton Reach Einhorn’s $450 Million EBITDA Goal?
Achieving Einhorn’s projected $450 million in EBITDA is ambitious but not impossible. Peloton’s current efforts to restructure and refinance its debt show it’s already taking steps toward greater financial health. Earlier this year, the company adjusted its debt load, a move that signaled to investors that Peloton was committed to a profitable, sustainable future.
However, hitting Einhorn’s EBITDA target would require even more discipline.
Despite the scale of these changes, Einhorn’s benchmark study suggests Peloton could pull it off. His comparisons to other subscription and fitness companies show that Peloton’s current spending habits are well above industry averages. By bringing costs in line with peers, Peloton could improve cash flow, reduce risk, and create a more predictable financial outlook.
What Could a $31.50 Peloton Stock Mean for Investors?
If David Einhorn’s vision for Peloton pans out, the financial rewards for investors could be substantial. A share price increase to $31.50 would be a five-fold increase from its recent trading level of around $6.20, representing a major upside for those willing to stick with the stock.
Einhorn’s pitch deck argued that with cost restructuring, Peloton could achieve the type of consistent profitability that has previously eluded it.
In recent years, Peloton focused heavily on customer acquisition and high-profile marketing efforts, often spending more than it brought in. Einhorn’s recommended shift would mean focusing less on rapid growth and more on stabilizing finances.